

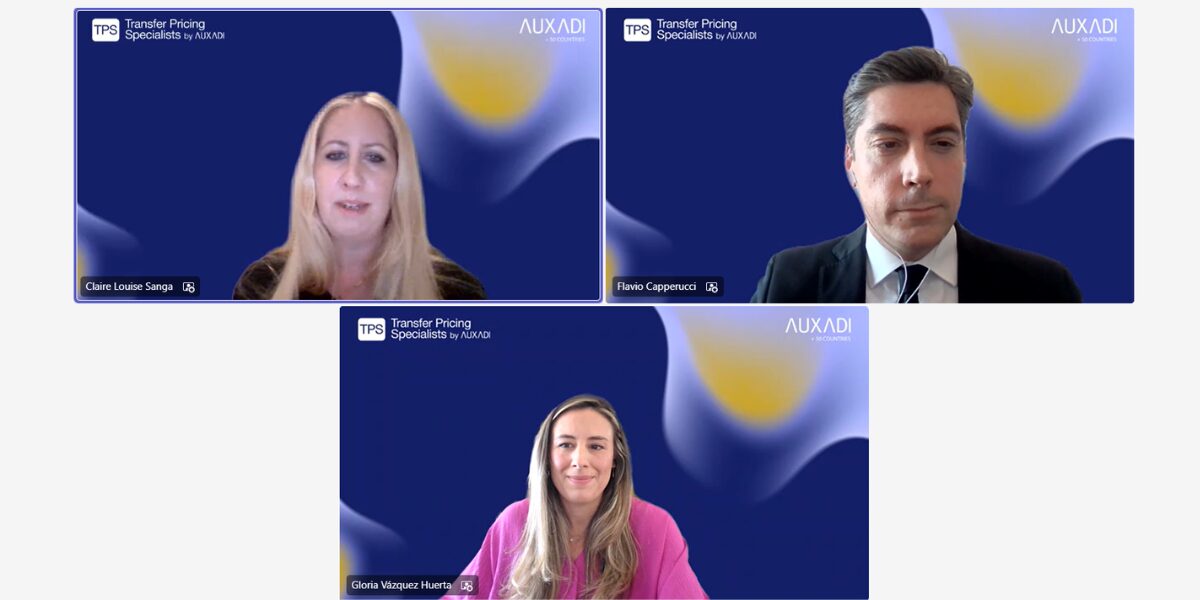
The webinar “Transfer Pricing Documentation”, held on March 18, brought together more than seventy online attendees interested in OECD standards and their impact on the transfer pricing policies of multinational groups. TPS by Auxadi organized the event with the participation of:
- Claire Sanga, Global VP of Transfer Pricing Services;
- Flavio Capperucci, Country Manager of Italy;
- Gloria Vázquez, Manager.
Monitoring OECD pillars
“One of the main differences [between countries] is the focus of the documentary obligation”, emphasized Gloria Vázquez. She detailed that “in Spain, the regulations clearly state that companies must have transfer pricing documentation justifying that their related-party transactions are carried out at market value”. On the other hand, Italy focuses on the “possibility of obtaining protection against penalties in the event of an adjustment by the tax administration”.
Claire Sanga clarified that “these are minimum requirements”, meaning “tax administrations could demand much more documentation“. For example, Spain highlights an “informative component” with obligations such as Form 232, noted Gloria Vázquez. Meanwhile, in Italy, it is a standard obligation to “digitally sign and time-stamp the documentation”, stated Flavio Capperucci.
Documentation subject to fines
Gloria Vázquez highlighted “three very common errors”. First, “documentation is prepared in a way that is too standardized”, the TPS by Auxadi Manager noted. This emphasis is because “the group’s business model does not always accurately reflect how operations truly work in practice”, leading her to recommend avoiding “overly general descriptions of functions and risks”.
Secondly, she added that “economic analyses or comparability studies are not updated regularly enough”, a key factor in determining “if they remain representative of current market conditions”. Finally, “the lack of consistency between different documents” becomes the third drawback in a world where “tax administrations increasingly use data analysis tools”.
However, these common rules must be adapted to the relevant tax systems. Despite following OECD standards, Germany has recently focused much of its supervision on the Local File. Furthermore, in 2025, the country expanded the required information with the introduction of the ‘Transaktionsmatrix’, “a summary table of related-party transactions”, summarized Flavio Capperucci.
Coordination and regulatory compliance
Claire Sanga believes it is “increasingly important to have a coordinated vision”. Given this situation, Gloria Vázquez advises organizing properly, especially when establishing “related-party transactions involving intangibles like fees or royalties” or “intragroup services”.
Correct transfer pricing documentation is fundamental for complying with tax obligations in countries under OECD tax policies. Thus, this webinar featured the three experts to assist CFOs in their international expansion.
TPS by Auxadi is the expert transfer pricing subsidiary of Auxadi. It operates in more than 50 countries, supporting clients in preparing and updating transfer pricing policies to comply with national and international regulations. This unit has been recognized for five consecutive years in Tier 1 of Transfer Pricing by the International Tax Review (ITR World Tax) ranking.
At Auxadi, we offer comprehensive services in accounting, tax, payroll, transfer pricing and corporate legal services to multinationals and funds. With experience since 1979 and a presence in over 50 countries, including 26 proprietary subsidiaries, our advanced technological platform, MySPV, and proven methodology enable us to guarantee efficient management in compliance with local regulations.
Author:
Auxadi Corporate
Watch the webinar “Transfer Pricing Documentation”:
Can Auxadi help?
Auxadi can become your ideal partner. We offer a one stop shop value added outsourcing services in the areas of accounting and reporting, tax compliance, payroll management and representation services, among others.
Local Knowledge – International Coverage
Founded in 1979, Auxadi is a family-owned business working for multinational corporations, private equity funds and real estate funds. It’s the leading firm in international accounting, tax compliance, payroll, transfer pricing, and corporate legal services management connecting Europe and the Americas with the rest of the world, offering services in 50 countries. Its client list includes many of the top 100 PERE companies. Headquartered in Madrid, with offices in US and further 26 international subsidiaries, Auxadi serves 1,500+ SPVs across 50 jurisdictions.
All information contained in this publication is up to date on 2026. This content has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this chart without obtaining specific professional advice.No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this content, and, to the extent permitted by law, AUXADI does not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this chart or for any decision based on it.