Chile: tax sanctions classification reform
The enactment of the Tax Compliance Law (Law 21,713) has introduced numerous changes directly impacting tax and auditing processes. This reform primarily affects tax sanctions in Chile, which are categorized into tax infractions and tax crimes.
Development of the law
Among the various matters covered by this Law, the modifications to sanctions are particularly noteworthy on this occasion. These changes specifically impact those described in Article 97 of the Tax Code, mainly affecting penalties associated with serious offenses and creating new criminal typifications.
The tax authority (SII) has published Circular No. 33/2025, which clarifies the concepts of tax infraction (lesser severity) and tax crime (greater severity). Regarding infractions, changes have been introduced primarily related to the keeping of accounting books and the issuance of tax documents. On the other hand, a tax crime is defined as “conduct corresponding to the authorization of folios for electronic tax documents, by digital means and with the knowledge that they will be used to defraud the Treasury”, according to the circular statement.
Reform in considerations
To understand the changes made to the classifications of tax infractions and crimes in depth, the following are the most relevant for legal entities with a presence in Chile:
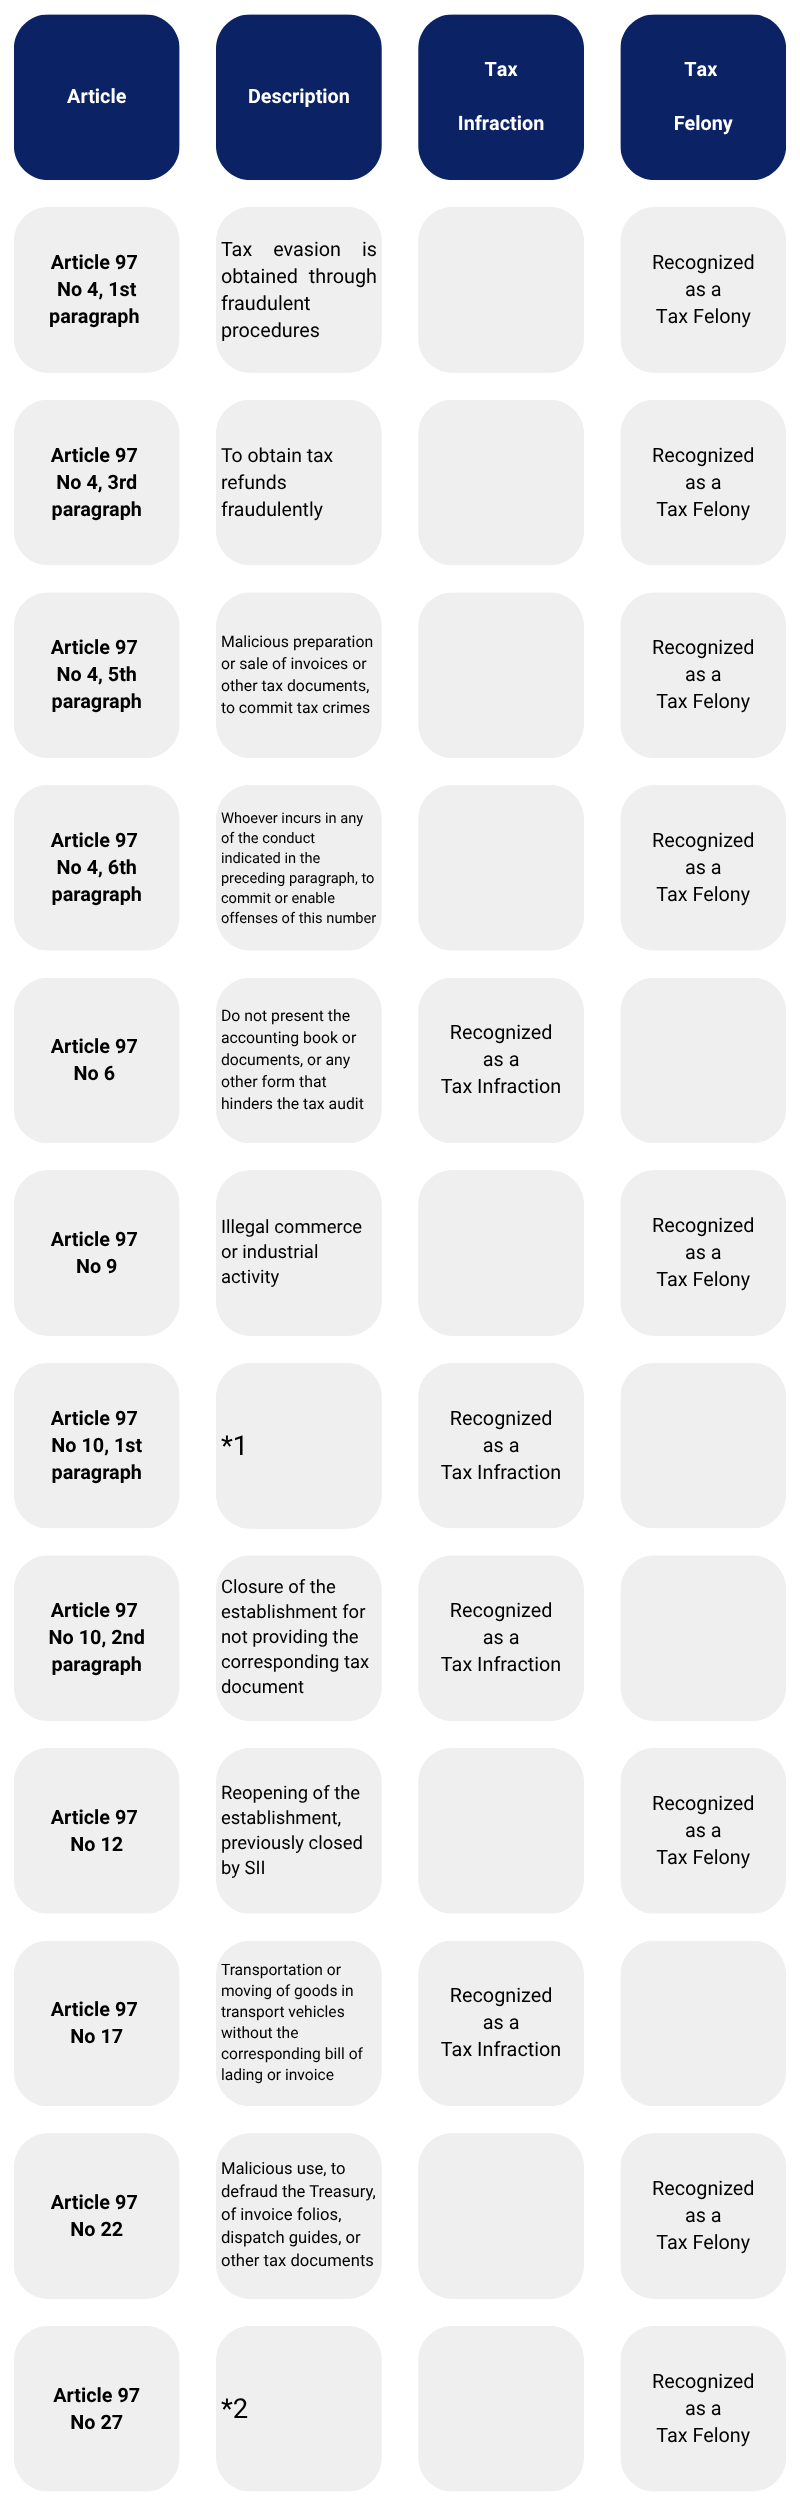
*1 Do not provide or provide the tax documents without the minimum requirements of invoices, receipts, credit or debit notes, or dispatch notes. Subdivision of the sales amount to avoid the issuance of receipts
*2 Executing acts or contracts to reduce assets or increase liabilities, when it has become knowledgeable of the start of an administrative or judicial proceeding, without economic or legal justification, other than harming the administration or frustrating the fulfillment of tax obligations
Conclusions
Latin American states are increasingly scrutinizing companies, aiming to boost state revenue, enhance entity transparency, and ensure regulatory compliance. Therefore, Chile is joining this trend with increased sanction levels for non-compliant taxpayers.
Managing legal and tax obligations can be challenging when you handle assets across different jurisdictions. Do not hesitate to contact us for our tax services in Chile or in the over 50 countries where we operate.
We invite you to contact us via our form for a personalized consultation.
At Auxadi, we offer comprehensive services in accounting, tax, payroll, and corporate legal services to multinationals and funds. With experience since 1979 and a presence in over 50 countries, including 22 proprietary subsidiaries, our advanced technological platform and proven methodology enable us to guarantee efficient management in compliance with local regulations.
Can Auxadi help?
Auxadi can become your ideal partner. We offer a one stop shop value added outsourcing services in the areas of accounting and reporting, tax compliance, payroll management and representation services, among others.
Local Knowledge – International Coverage
Founded in 1979, Auxadi is a family-owned business working for multinational corporations, private equity funds and real estate funds. It’s the leading firm in international accounting, tax compliance, payroll, transfer pricing, and corporate legal services management connecting Europe and the Americas with the rest of the world, offering services in 50 countries. Its client list includes many of the top 100 PERE companies. Headquartered in Madrid, with offices in US and further 26 international subsidiaries, Auxadi serves 1,500+ SPVs across 50 jurisdictions.
All information contained in this publication is up to date on 2024. This content has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this chart without obtaining specific professional advice.No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this content, and, to the extent permitted by law, AUXADI does not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this chart or for any decision based on it.