

Portugal has implemented modifications to its Corporate Income Tax (CIT) rates, impacting entities based on the location of their registered office and other branches within the national territory.
The new provisions establish a differential withholding system rooted in geography. The regions of Madeira and the Azores archipelago will apply a lower tax rate, whereas the mainland territory will apply the standard general CIT rate.
Tiers by industry and size
The Portuguese tax system also establishes a distinction based on the size of the entity:
- Small and Medium-sized Enterprises (SMEs) will be subject to a reduced rate of 16% on the first € 50,000 of the taxable base.
- All other entities (including large corporations or other categorizations) will be subject to the general rate of 20% (with the exception of the island territories of Madeira and the Azores Islands).
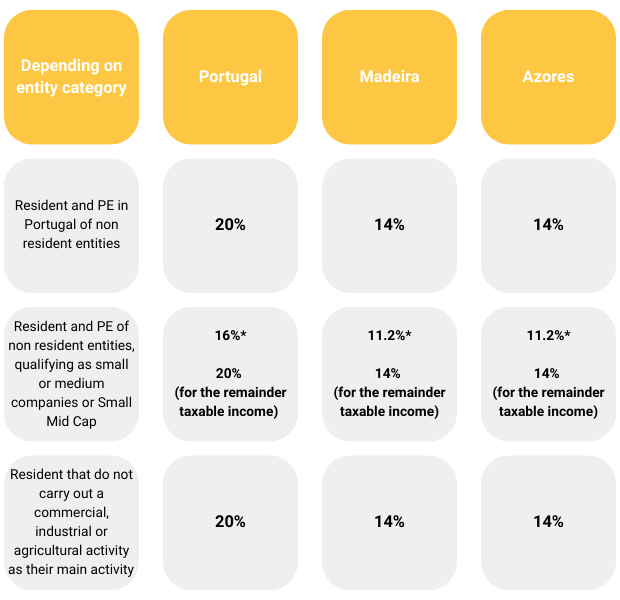
*for the first € 50.000 of taxable income
Non-commercial, non-industrial, and non-agricultural companies are obligated to declare Portuguese CIT at 20%, in the same way as companies in the first tier.
CIT reduction in Portugal
Micro, small, or medium-sized companies that carry out their activity and have their effective management in inland areas (Decree 208/2017, of July 13) can benefit from a reduced rate. This option is available for small and medium-capitalization companies (Small Mid Cap), including those qualified as start-ups.
The recent Law No. 64/2025, of November 7, will progressively reduce the nominal standard Corporate Income Tax (CIT) rate for companies. This reduction will follow the schedule below:
- from 20% to 19% in 2026 tax year;
- to 18% in 2027;
- and to 17% in 2028.
Likewise, for Small Mid Cap companies, the first € 50,000 of taxable income shall be taxed at only 15%.
Tax update in 2025
The current Government of Portugal has developed a continued policy of tax simplification, a measure specifically aimed at businesses. A few months ago, it updated the monthly minimum wage and the subsidies introduced in Portuguese payrolls. Finally, it reduced the rates imposed on the acquisition of vehicles.
Therefore, if you are a multinational interested in expanding into Portugal, you can rely on Auxadi’s accounting services to support your internationalization process.
At Auxadi, we offer comprehensive services in accounting, tax, payroll, transfer pricing and corporate legal services to multinationals and funds. With experience since 1979 and a presence in over 50 countries, including 26 proprietary subsidiaries, our advanced technological platform and proven methodology enable us to guarantee efficient management in compliance with local regulations.
Can Auxadi help?
Auxadi can become your ideal partner. We offer a one stop shop value added outsourcing services in the areas of accounting and reporting, tax compliance, payroll management and representation services, among others.
Local Knowledge – International Coverage
Founded in 1979, Auxadi is a family-owned business working for multinational corporations, private equity funds and real estate funds. It’s the leading firm in international accounting, tax compliance, payroll, transfer pricing, and corporate legal services management connecting Europe and the Americas with the rest of the world, offering services in 50 countries. Its client list includes many of the top 100 PERE companies. Headquartered in Madrid, with offices in US and further 26 international subsidiaries, Auxadi serves 1,500+ SPVs across 50 jurisdictions.
All information contained in this publication is up to date on 2024. This content has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this chart without obtaining specific professional advice.No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this content, and, to the extent permitted by law, AUXADI does not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this chart or for any decision based on it.